House Hacking: How to Buy a Home, Live in One Unit, and Rent the Other
Updated: Sep 5
House hacking is becoming a popular way for buyers to make homeownership more affordable while starting to think like real estate investors. In this article, you’ll learn how house hacking works, what it means to buy a multi-family home, how you can live in one unit and rent the other, and what to consider before using this strategy.

Buying a home can feel expensive, especially when you are trying to manage a down payment, monthly mortgage payment, closing costs, and everyday living expenses. That is why more buyers are looking at house hacking as a way to make homeownership more affordable.
House hacking is a real estate strategy where you buy a property, live in part of it, and rent out another part to help offset your housing costs. For some buyers, that may mean buying a multi-family home, living in one unit, and renting out the other. For others, it may mean renting out a room, guest suite, basement apartment, or separate living space.
For the right borrower and property, a house hacking mortgage can be a powerful way to start building equity, reduce your personal housing expense, and enter real estate investing while still buying a primary residence.
What You’ll Learn in This Article:
What Is House Hacking?
House hacking is when you use part of your home to generate rental income while you also live there. The most common example is simple:
You buy a duplex, triplex, or four-unit property. You live in one unit and rent the other unit or units.The rental income may help cover part of the mortgage payment.
This is why house hacking can be especially interesting for first-time buyers. Instead of buying only a single-family home, some buyers consider a first-time buyer investment property approach by purchasing a small multi-family property that also serves as their primary residence.
The goal is not just to buy a home. The goal is to buy a home in a way that may also help create long-term financial flexibility.
How a House Hacking Mortgage Works
A house hacking mortgage is not always a separate loan category. In many cases, it means using a mortgage program that allows you to buy an eligible property as your primary residence while renting out another part of the property.
For example, a buyer may purchase a two-unit, three-unit, or four-unit property and occupy one of the units as their primary residence. The remaining unit or units may be rented out, depending on loan guidelines, property rules, and local requirements.
Because you are living in the property, this may be treated differently from buying a purely investment property where you do not live there. That distinction can matter when comparing mortgage options, down payment requirements, occupancy rules, and qualification guidelines.
This is why it is important to speak with a mortgage professional before assuming which loan will work – contact us to review your goals in New Jersey or Florida and better understand which mortgage path may fit your situation.
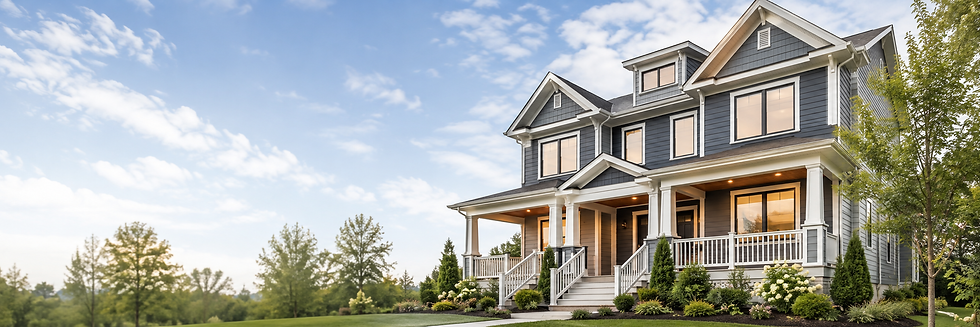
Buying a Multi-Family Home for House Hacking
One of the most common house hacking strategies is buying a multi-family home.
This usually means purchasing a property with two to four units, such as: A duplex, a triplex or a fourplex.
The buyer lives in one unit and rents out the other unit or units. This strategy can be attractive because the property is still your home, but it may also produce income.
For example, a buyer could live in one side of a duplex and rent the other side to a tenant. The rental income may help reduce the effective monthly cost of owning the property.
However, multi-family properties can also come with additional responsibilities. You may need to think about tenant screening, leases, maintenance, reserves, property condition, local rental rules, and whether you are comfortable being both a homeowner and a landlord.
Can House Hacking Work for First-Time Buyers?
Yes, house hacking can potentially work for first-time buyers, but it depends on the borrower, the property, and the loan program.
A first-time buyer investment property strategy can sound confusing because the buyer is still purchasing a primary residence. The difference is that the property may also include rental income potential.
This can be appealing because the buyer is not necessarily waiting years to become a real estate investor. They may be able to start with a small multi-family property, live there, and learn how rental property ownership works while still using the home as their primary residence.
That said, not every buyer is ready for the responsibilities that come with tenants or a multi-unit property. House hacking can be a smart strategy, but it should be planned carefully.
Therefore, before exploring house hacking, make sure you understand the mortgage basics like pre-approval, down payments, closing costs, and credit. Read our First-Time Buyer Guide to get started.
What Lenders May Look At
When applying for a mortgage for a house hacking strategy, lenders may review many of the same things they review for other home loans, including: Credit history, Income, Employment, Assets, Debt-to-income ratio, Down payment funds, Property type, Occupancy and Loan program guidelines
If the property includes rental units, the lender may also consider whether rental income can be used to help qualify. This depends on the loan program, property, lease details, appraisal, and underwriting guidelines.
This is another reason to get guidance early. You want to know whether the property type and income strategy actually match the mortgage program you plan to use.

Benefits of House Hacking
House hacking may offer several possible benefits for the right buyer.
It may help reduce your personal housing cost. It can introduce you to real estate investing. It may help you build equity while collecting rental income. It can be a way to buy a larger or more strategic property. It may support long-term wealth-building goals.
For some buyers, house hacking is the bridge between buying a first home and becoming a real estate investor.
Things to Consider Before House Hacking
House hacking is not just about the mortgage. It is also about lifestyle, responsibility, and planning.
Before buying a multi-family home or renting out part of your property, think about:
Are you comfortable living near your tenants?Do you understand local rental rules?Can you handle repairs and maintenance?Do you have reserves if a unit is vacant?Will the property condition meet lending requirements?Are you prepared for landlord responsibilities?Does the loan program allow your intended use?
House hacking can be a great strategy, but it works best when buyers understand both the opportunity and the responsibility.
House Hacking vs. Traditional Investment Property
A traditional investment property is usually a home you buy specifically to rent out, without living there. House hacking is different because you live in the property as your primary residence while renting part of it.
That difference may affect the mortgage conversation. A primary residence may have different loan options than a non-owner-occupied investment property. However, you must be honest about how you plan to use the property. Occupancy matters in mortgage lending.
If you plan to live in one unit and rent the other, tell your mortgage professional clearly from the beginning. That helps ensure the loan structure, property type, and documentation are reviewed correctly.

Is House Hacking Right for You?
House hacking may be a good fit if you want to buy a home and are open to using rental income as part of your long-term strategy. It may be especially interesting if you are considering a duplex, triplex, fourplex, or another property that gives you a separate space to rent.
It may not be the right fit if you do not want to manage tenants, handle additional maintenance, or live in a property with renters nearby.
The best next step is to compare your options before you start making offers. A mortgage professional can help you understand what may be possible based on your goals, budget, property type, and loan program.
Thinking About House Hacking?
House hacking can be a smart way to approach homeownership, especially if you are interested in buying a multi-family home, living in one unit, and renting the other. But the right mortgage strategy depends on your financial situation, the property, and the loan options available to you.
At Manos Mortgage, we can help you understand your options in New Jersey or Florida before you make your next move.
Explore More Mortgage Resources
House hacking is only one way to think strategically about homeownership. To keep learning, explore more resources from Manos Mortgage, including our First-Time Buyer Guide, Mortgage Loan Options, Mortgage Glossary, Mortgage Do’s and Don’ts, and Mortgage Calculator. These resources can help you better understand the mortgage process, compare loan options, learn important terms, and prepare for your next step with more confidence.
Disclaimer: This article is for educational purposes only and is not a commitment to lend. Loan approval, interest rates, down payment requirements, rental income use, occupancy rules, and program eligibility depend on borrower qualifications, property details, lender guidelines, market conditions, and applicable requierments.


